
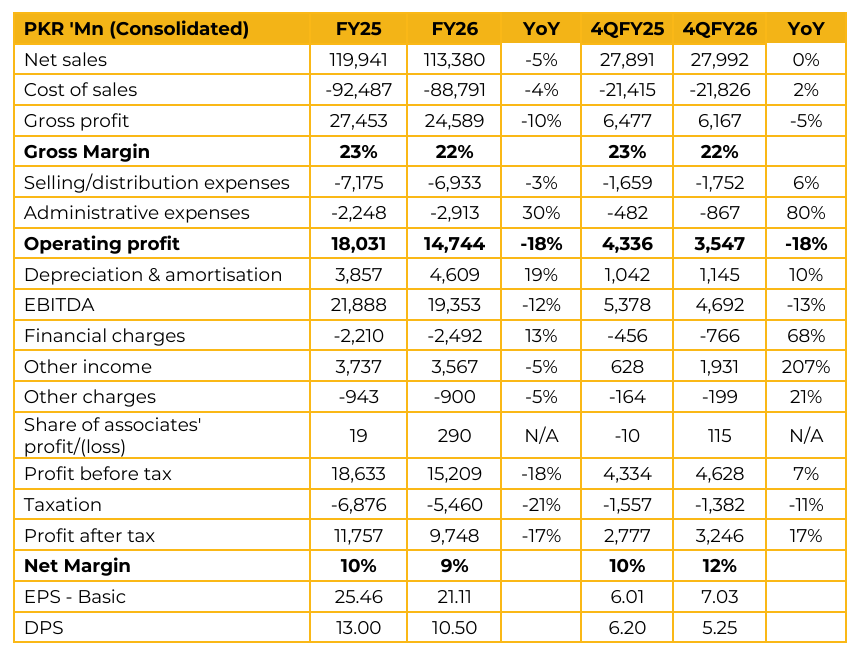
Lucky Core Industries Limited (LCI) reported earnings per share of PKR 21.11 for FY26, compared to earnings per share of PKR 25.46 in FY25. Furthermore, in 4QFY26, the company reported earnings per share of PKR 7.03, compared to earnings per share of PKR 6.01 in the same period last year (SPLY). In the soda ash segment, full year sales volume declined to 424,000 metric tons, compared with 452,000 tons in the prior year. Q4 sales volume stood at 98,000 tons, versus 111,000 tons in the corresponding quarter last year.
Domestic volumes grew by 6% YoY, while export volumes fell by 60% YoY, reflecting intense pressure from Chinese dumping in global markets. Capacity utilization averaged 70%–80%, against a maximum operational capacity of 135,000–138,000 tons. Gross selling prices ranged between PKR 96,000 and PKR 100,000 per ton. Substantial volume based dealer discounts, averaging PKR 12,000–13,000 per ton, brought net average realization to approximately PKR 88,000 per ton, as the company sought to protect its domestic market share against low priced imports.
Approximately 95% of energy requirements are met through coal, comprising an equal mix of domestic and imported coal, supplemented by biomass. The previously approved 200,000 ton expansion project, with estimated capex of USD 140 million, has been placed on hold amid subdued market demand and low capacity utilization. The National Tariff Commission (NTC) imposed provisional anti dumping duties of 10.83%–35% on imports from China, 12% on Kenya, and 4.5%–6% on Turkey. In the polyester staple fibre (PSF) segment, full year sales volume stood at approximately 94,000 tons, including 21,000 tons in Q4.
Chinese PSF imports were priced PKR 30–35 per kg below local production costs for most of the year. However, a recent doubling of global shipping freight rates brought landed import prices broadly in line with local prices at approximately PKR 445 per kg. The segment operates primarily on gas, with a mix of 75% natural gas and 25% RLNG. In the pharmaceutical segment, border closures with Afghanistan resulted in the loss of approximately PKR 2.0 billion in annual export sales, weighing on volume growth. Sales volumes declined by 1%, offset by a 6% increase in prices. Volume growth in the masterbatch and specialty chemicals businesses was offset by earnings compression in the Agri business, reflecting disrupted crop cycles over the past 2–3 years. In the animal health segment, growth is being driven by double digit volumetric gains across the poultry and livestock sectors through the Farmer’s Choice portfolio.
The newly commissioned Veterinary Medicine Plant commenced operations during the year, which management expects to support further volume growth. Management reiterated that LCI has historically distributed approximately 50% of net earnings to shareholders and expects to maintain this 50% payout ratio going forward
Important Disclosures
Disclaimer: This report has been prepared by Chase Securities Pakistan (Private) Limited and is provided for information purposes only. Under no circumstances, this is to be used or considered as an offer to sell or solicitation or any offer to buy. While reasonable care has been taken to ensure that the information contained in this report is not untrue or misleading at the time of its publication, Chase Securities makes no representation as to its accuracy or completeness and it should not be relied upon as such. From time to time, Chase Securities and/or any of its officers or directors may, as permitted by applicable laws, have a position, or otherwise be interested in any transaction, in any securities directly or indirectly subject of this report Chase Securities as a firm may have business relationships, including investment banking relationships with the companies referred to in this report This report is provided only for the information of professional advisers who are expected to make their own investment decisions without undue reliance on this report and Chase Securities accepts no responsibility whatsoever for any direct or indirect consequential loss arising from any use of this report or its contents At the same time, it should be noted that investments in capital markets are also subject to market risks This report may not be reproduced, distributed or published by any recipient for any purpose