
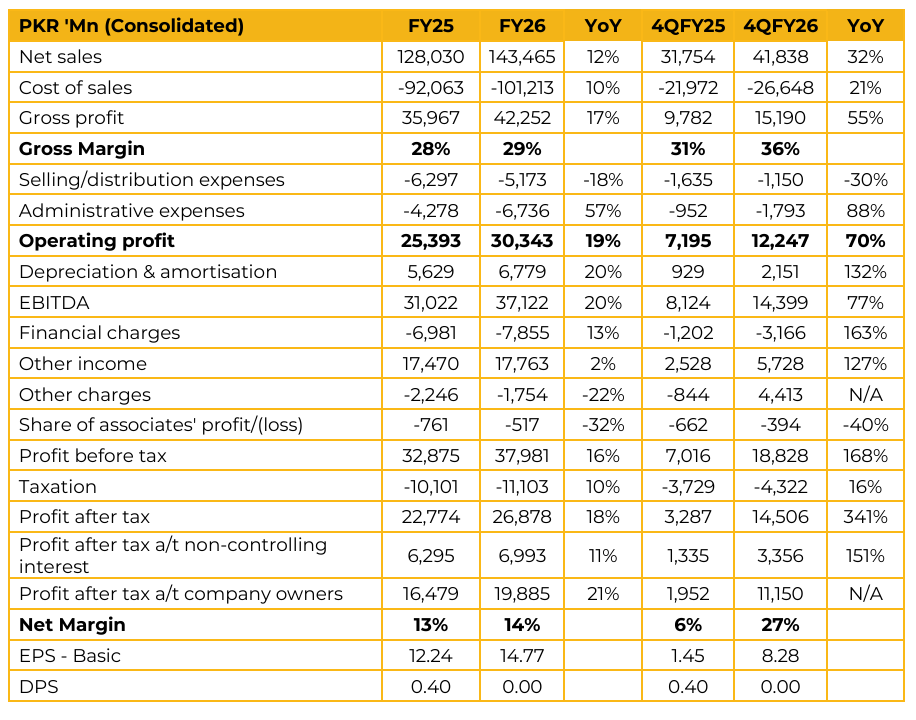
Kohinoor Textile Mills Limited (KTML) reported earnings per share of PKR 14.77 for FY26, compared to earnings per share of PKR 12.24 in FY25. Furthermore, in 4QFY26, the company reported earnings per share of PKR 8.28, compared to earnings per share of PKR 1.45 in the same period last year (SPLY). The company owns 58% of Maple Leaf Cement Factory Limited (MLCF) and 83% of Maple Leaf Capital Limited. The Home Textiles segment generates turnover of approximately PKR 15–16bn, with a gross margin of around 22.5%.
This division benefits from supplying high end, embellished bedding products to premium European retail brands. The Spinning Division generates turnover of approximately PKR 28–29bn, operating at a gross margin of around 14.5%. The Weaving Division generates turnover of around PKR 16bn, operating at a gross margin of 12.2%. Weaving remains a highly competitive and thin margin commodity business; however, KTML prioritizes quality to maintain a Tier-1 customer base with zero default risk. The raw cotton mix is approximately 85% local and 15% imported. Over 90% of total debt, amounting to more than PKR 10bn, is secured under concessionary central bank export schemes.
The company’s average borrowing cost remains exceptionally low at 5.5% pre-tax. Europe’s share expanded to 56% of total exports in FY26, as European markets offer superior gross margins and greater pricing stability. The company has deliberately reduced its exposure to the US market from 55% several years ago to 32%, in order to limit exposure to unpredictable US tariff revisions and high volume, margin dilutive retail accounts. Margins are protected by shifting toward highly embellished, labor intensive home textile products, where retail prices are higher and competitors cannot easily match quality. Providing on site worker housing helps ensure low turnover and consistent tailoring quality, supporting the company’s focus on serving premium brands. Total connected continuous industrial load across all three sites stands at 24.41MWH, while the current solar base is 5.5MW.
The company plans to add 9–10MW of solar capacity, alongside a PKR 2.0bn Battery Energy Storage System (BESS) project at the Rawalpindi site. The project is expected to generate annualized cost savings of approximately PKR 600mn. The REER stands overvalued at 107–108. With the rupee devaluing by only 1.0–1.5%, local exporters face an effective 11–12% increase in real production costs, which cannot be passed on to international buyers. Cotton price volatility is managed by strictly covering raw material purchases against locked customer sales orders. KTML’s monthly raw cotton consumption is only 10,000–11,000 bales. Local cotton remains 10–15% cheaper than imported cotton, and KTML has adapted its processes to effectively handle shorter domestic staple lengths.
Important Disclosures
Disclaimer: This report has been prepared by Chase Securities Pakistan (Private) Limited and is provided for information purposes only. Under no circumstances, this is to be used or considered as an offer to sell or solicitation or any offer to buy. While reasonable care has been taken to ensure that the information contained in this report is not untrue or misleading at the time of its publication, Chase Securities makes no representation as to its accuracy or completeness and it should not be relied upon as such. From time to time, Chase Securities and/or any of its officers or directors may, as permitted by applicable laws, have a position, or otherwise be interested in any transaction, in any securities directly or indirectly subject of this report Chase Securities as a firm may have business relationships, including investment banking relationships with the companies referred to in this report This report is provided only for the information of professional advisers who are expected to make their own investment decisions without undue reliance on this report and Chase Securities accepts no responsibility whatsoever for any direct or indirect consequential loss arising from any use of this report or its contents At the same time, it should be noted that investments in capital markets are also subject to market risks This report may not be reproduced, distributed or published by any recipient for any purpose.