
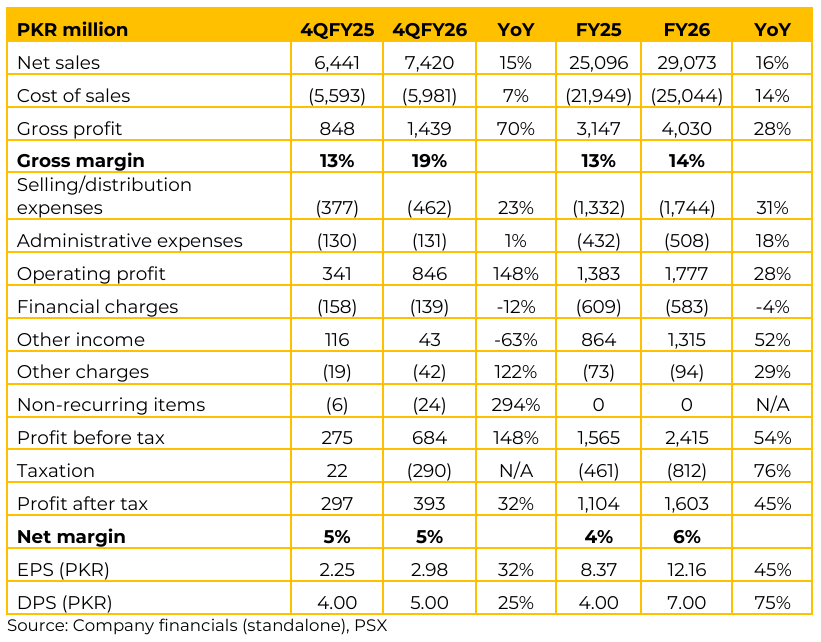
In FY26, INIL reported a net turnover of PKR 29 billion as compared to PKR 25 billion in SPLY. The gross margin increased to 14% from 13% during the same period. The company posted profit after tax of PKR 1.6 billion (EPS: PKR 12.16) in FY26 as compared to PKR 1.1 billion (EPS: PKR 8.37) in the SPLY. Domestic Steel segment served as the primary revenue engine, expanding by 36.7% YoY. Growth was predominantly fueled by a 20% demand surge in the domestic automotive manufacturing sector, a key consumer of INIL tubing.
Polymer segment underperformed during the year due to a drop in institutional tenders and project announcements from the two state gas utility companies (SSGC and SNGPL). However, recovery is anticipated in FY27 as infrastructure spending resumes. Export segment accounted for 10.4% (PKR 3.1 billion) of turnover. Exports faced margin pressures from elevated ocean freight rates and global trade barriers. INIL expanded its new Engineering Solutions segment, launched four dedicated business divisions covering Construction, Renewable Energy, Agri, and Material Handling Solutions. The company, alongside other group entities, initiated the divestment of its stake in Chinoy Engineering and Construction Private Limited (CCL) following the cancellation of the Reko Diq Phase 2 accommodation project. IIL Trading Private Limited is a wholly owned subsidiary acting as a brand representational hub for overseas industrial products: Fisher (Germany – fixings/fasteners), Milwaukee (USA – power tools), and Mapei (Italy – building chemicals). INIL also launched the UPVC segment while expanding PPRC and HDPE product lines. The company discontinued captive gas-based power generation as it became economically unviable (PKR 50/kWh for captive gas vs. PKR 40/kWh grid tariff). Power mix stands at 70% Grid / 30% Solar, supported by 4 MW of captive solar capacity (generating 4.85 GWh). Management is currently evaluating Battery Energy Storage Systems (BESS) for further energy cost optimization.
In FY26, INIL made an equity investment in CFS Minerals to explore opportunities in Pakistan’s mining sector across Khyber Pakhtunkhwa and Balochistan. The venture remains in the exploratory phase, with active work set to begin in coming years. Target areas in KPK remain insulated from regional security challenges. CRC represents approximately 20% of IIL’s overall raw material sales mix.
Nearly 100% of CRC requirements are purchased from sister company International Steels Limited. While HRC is sourced externally, since ISL doesn’t produce HRC. The domestic pipe market remains heavily distorted, split 40% organized vs. 60% unorganized.
Despite tariff rationalization on imported pipes, high freight costs act as a natural barrier to entry. Importing hollow pipes requires paying freight on “trapped air,” making foreign finished pipes cost-prohibitive compared to locally manufactured products. Going forward, management remains bullish on construction and automotive sector demand. While volume growth will normalize from FY26’s high base, management expects sustainable double digit growth to continue. Institutional gas project volume slowdown impacted FY26 polymer performance, but public sector infrastructure projects and UPVC launch are expected to drive recovery in FY27.
Important Disclosures
Disclaimer: This report has been prepared by Chase Securities Pakistan (Private) Limited and is provided for information purposes only. Under no circumstances, this is to be used or considered as an offer to sell or solicitation or any offer to buy. While reasonable care has been taken to ensure that the information contained in this report is not untrue or misleading at the time of its publication, Chase Securities makes no representation as to its accuracy or completeness and it should not be relied upon as such. From time to time, Chase Securities and/or any of its officers or directors may, as permitted by applicable laws, have a position, or otherwise be interested in any transaction, in any securities directly or indirectly subject of this report Chase Securities as a firm may have business relationships, including investment banking relationships with the companies referred to in this report This report is provided only for the information of professional advisers who are expected to make their own investment decisions without undue reliance on this report and Chase Securities accepts no responsibility whatsoever for any direct or indirect consequential loss arising from any use of this report or its contents At the same time, it should be noted that investments in capital markets are also subject to market risks This report may not be reproduced, distributed or published by any recipient for any purpose.