
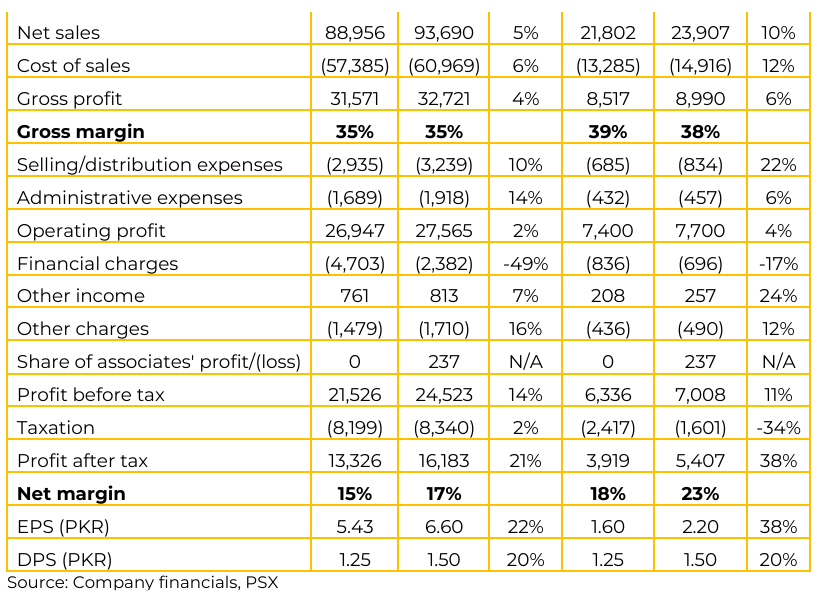
Fauji Cement Company Limited (FCCL) reported earnings per share of PKR 6.60 for FY26 (FY25: PKR 5.43). Furthermore, in 4QFY26, the company reported earnings per share of PKR 2.20 (4QFY25: PKR 1.60). Net revenues grew 6% YoY to PKR 94 billion, supported by a 12.5% growth in domestic cement dispatches (5.41 Mn tons), offsetting a 48% decline in export sales (0.29 Mn tons) caused by the Afghan border closure.
Cost of Production (COP) per ton dropped slightly from PKR 10,723/ton in FY25 to PKR 10,659/ton in FY26. Expansion of PP bag capacity at Hattar to 108 million bags p.a. now fulfills 100% of internal packaging needs in-house (contributing 89% to overall bag usage vs. 35% last year). Management noted that fuel cost per ton was reduced to PKR 4,149 in FY26 from PKR 4,376 in SPLY, due to higher utilization of cheaper local coal, despite higher spot coal prices.
Similarly, in FY26 power cost per ton remained PKR 1,610 (FY25: PKR 1,378), impacted by grid power rate revisions, partially mitigated by expanded solarization and lower WAPDA tariffs. Cement dispatch capacity utilization stood at 55% (2% above the industry average), yielding a national market share of 16%. Total dispatches reached 5.70 million tons. FCCL, jointly with KAPCO, acquired an aggregate ~92% stake in Attock Cement Pakistan Limited. FCCL’s specific shareholding is 46%, financed through PKR 13 billion in foreign debt and PKR 7 billion in internal cash generation. Captive power capacity stands at 133.5 MW, including 70 MW (expandable/operational up to ~75.4 MW) solar and 48 MW Waste Heat Recovery (WHR).
Renewable energy accounted for 51% of the power mix, helping offset inflationary cost pressures and reducing carbon emissions by 187,000 tons of CO₂. FCCL holds the distinction of being approved for all major national hydropower projects, benefiting from strict technical qualification standards. Key supply projects include the Diamer-Bhasha Dam, Dasu Hydropower Project, and Mohmand Dam. Major institutional buyers include the Frontier Works Organisation (FWO), National Logistics Cell (NLC), Army Housing Scheme, and Defense Housing Authority (DHA).
In FY26, retention per ton remained PKR 870 and PKR 875 per bag, currently standing at PKR 900 per bag. Fuel mix comprises approximately 75% local coal and 25% imported coal. Sourcing choices are dynamically adjusted based on the lowest per-MMBtu heat cost. Local/Afghan coal is prioritized due to cost advantages; imported coal is sourced via sea from South Africa and Mozambique. Average local coal cost was approximately PKR 40,000 per ton during FY26. Going forward, management’s outlook for FY26–27 remains cautiously positive. Growth will be driven primarily by domestic volume demand (housing and PSDP projects), while exports will remain dependent on border policy resolutions. Management projects company’s domestic dispatch growth of 8% to 10%.
Important Disclosures
isclaimer: This report has been prepared by Chase Securities Pakistan (Private) Limited and is provided for information purposes only. Under no circumstances, this is to be used or considered as an offer to sell or solicitation or any offer to buy. While reasonable care has been taken to ensure that the information contained in this report is not untrue or misleading at the time of its publication, Chase Securities makes no representation as to its accuracy or completeness and it should not be relied upon as such. From time to time, Chase Securities and/or any of its officers or directors may, as permitted by applicable laws, have a position, or otherwise be interested in any transaction, in any securities directly or indirectly subject of this report Chase Securities as a firm may have business relationships, including investment banking relationships with the companies referred to in this report This report is provided only for the information of professional advisers who are expected to make their own investment decisions without undue reliance on this report and Chase Securities accepts no responsibility whatsoever for any direct or indirect consequential loss arising from any use of this report or its contents At the same time, it should be noted that investments in capital markets are also subject to market risks This report may not be reproduced, distributed or published by any recipient for any purpose.