
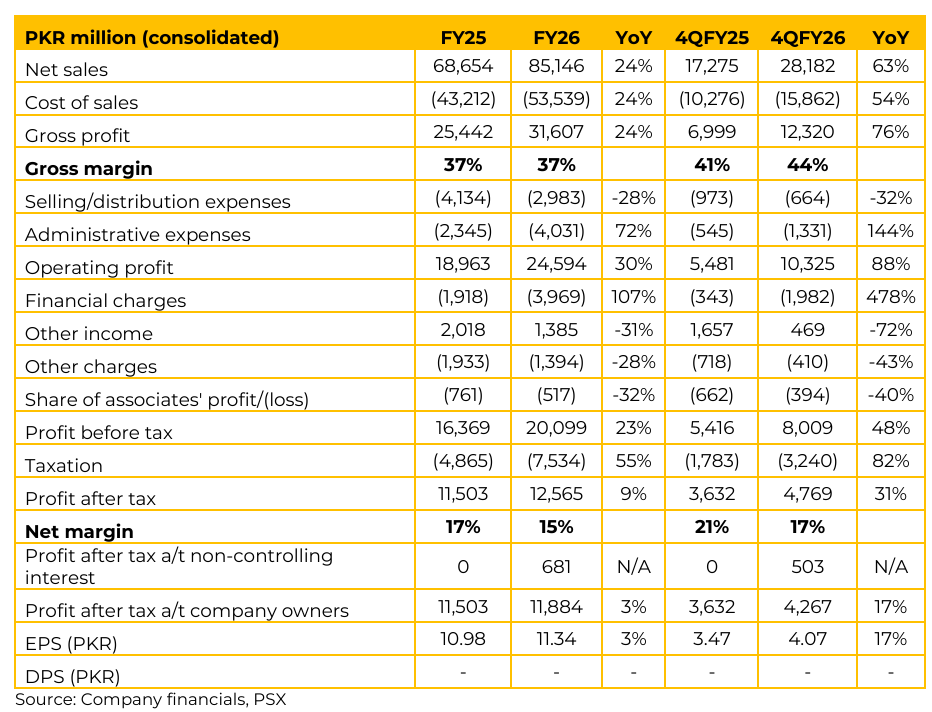
Maple Leaf Cement Factory Limited (MLCF) reported standalone earnings per share of PKR 8.06 for FY26 (FY25: PKR 16.26). On a consolidated basis, the EPS stood at PKR 11.34 in FY26 (FY25: PKR 10.98). Management noted that following four years of negative growth, the cement industry experienced a recovery in FY2026 (~10% growth; currently pacing at 7% to 7.5%). Domestic capacity utilization across Pakistan remains muted at 51% (North at 54%, South at 41%).
Geopolitical conflicts and international market volatility have pushed fuel and freight costs up across the board by approximately 40%. Darra coal currently trades at PKR 62,000 to 63,000 per ton, with heating values between 6,200 and 6,500 kcal/kg. The management holds adequate inventory of pet coke & coal, sufficient for 3-4 months. Retention prices have remained relatively flat; recent price hikes represent a direct pass-through of rising fuel and transportation expenses to preserve contribution margins. Average power cost stands at 6.7 cents/kWh (PKR 18.85/unit).
MLCF is aggressively transitioning Pioneer away from its inefficient coal plant toward national grid power (leveraging incremental tariff packages), solar additions (31 MW at Pioneer), and alternative fuels. A captive solar power setup of 31MW at Pioneer is under execution and slated for commissioning by December 2026 / January 2027. AF/biomass firing capabilities at Pioneer will commence in January 2027. Replicating MLCF’s logistics framework at Pioneer is projected to yield an additional ~PKR 70/ton savings within the next two months.
Management has already successfully implemented 50% to 60% of MLCF’s operational practices at Pioneer. Management is keeping Maple and Pioneer as two separate brands and independent sales networks to foster internal competition. This management push enabled Pioneer’s sales team to optimize pricing and realize its full location advantage bringing its retention to PKR 250/ton above MLCF.
MLCF holds a strategic equity position of Faysal bank just under 5%, with State Bank of Pakistan (SBP) “fit and proper” clearance to acquire up to 10%, subject to cash flow and market supply conditions. MLCF possesses dedicated railway sidings connecting plants to the port for direct coal movement.
However, current Pakistan Railways wagon diversions to national priority energy projects have forced a temporary mix of rail and road transportation. Going forward, management forecasts baseline industry growth of 7.0% to 7.5% over the near term. If government housing initiatives (such as the Apna Ghar Scheme) gain substantial traction, growth could reach 10%. Novacare’s civil construction completion is targeted between March and June 2026 (delayed 3–6 months) due to equipment shipping delays via the Straits of Hormuz.
Important Disclosures
Disclaimer: This report has been prepared by Chase Securities Pakistan (Private) Limited and is provided for information purposes only. Under no circumstances, this is to be used or considered as an offer to sell or solicitation or any offer to buy. While reasonable care has been taken to ensure that the information contained in this report is not untrue or misleading at the time of its publication, Chase Securities makes no representation as to its accuracy or completeness and it should not be relied upon as such. From time to time, Chase Securities and/or any of its officers or directors may, as permitted by applicable laws, have a position, or otherwise be interested in any transaction, in any securities directly or indirectly subject of this report Chase Securities as a firm may have business relationships, including investment banking relationships with the companies referred to in this report This report is provided only for the information of professional advisers who are expected to make their own investment decisions without undue reliance on this report and Chase Securities accepts no responsibility whatsoever for any direct or indirect consequential loss arising from any use of this report or its contents At the same time, it should be noted that investments in capital markets are also subject to market risks This report may not be reproduced, distributed or published by any recipient for any purpose.